Three plans: El Resumen Esencial for free, Premium with the full analysis and Intelligence with data and alerts to decide, in English, Spanish or Portuguese.
Three plans: El Resumen Esencial for free, Premium with the full analysis and Intelligence with data and alerts to decide, in English, Spanish or Portuguese.
Three plans: El Resumen Esencial for free, Premium with the full analysis and Intelligence with data and alerts to decide, in English, Spanish or Portuguese.
+Enfoque · Finance
In September, family loan delinquency in Argentina decreased for the second consecutive month. However, refinancing occurrences reached a 15-year high, reflecting ongoing financial challenges.
Perfil4 min read
Main framing
Left 70%
Left · estimated by AI · 80% confidence
The estimate comes from analyzing the story's text: which sources it quotes, which facts it highlights and what language it uses.
An AI model reads the story and estimates how much of its framing leans left, center or toward a libertarian view. The three percentages add up to 100.
This is an AI-generated estimate, not an objective judgment.
Generated on · 1 min read
AI summaries may contain errors.
Finance · La Nación
Finance · El Cronista
Finance · iProfesional
Finance · Ámbito
Finance · iProfesional
AI estimate · 80% confidence
The report emphasizes BCRA data on refinancing increases but lacks government perspectives.
La morosidad de las familias registró una nueva baja en septiembre y acumuló su segundo descenso mensual consecutivo, aunque los niveles de endeudamiento continúan elevados en comparación con el año pasado. Al mismo tiempo, creció la cantidad de créditos refinanciados, una herramienta a la que recurren los hogares para reorganizar sus compromisos financieros y evitar mayores atrasos.
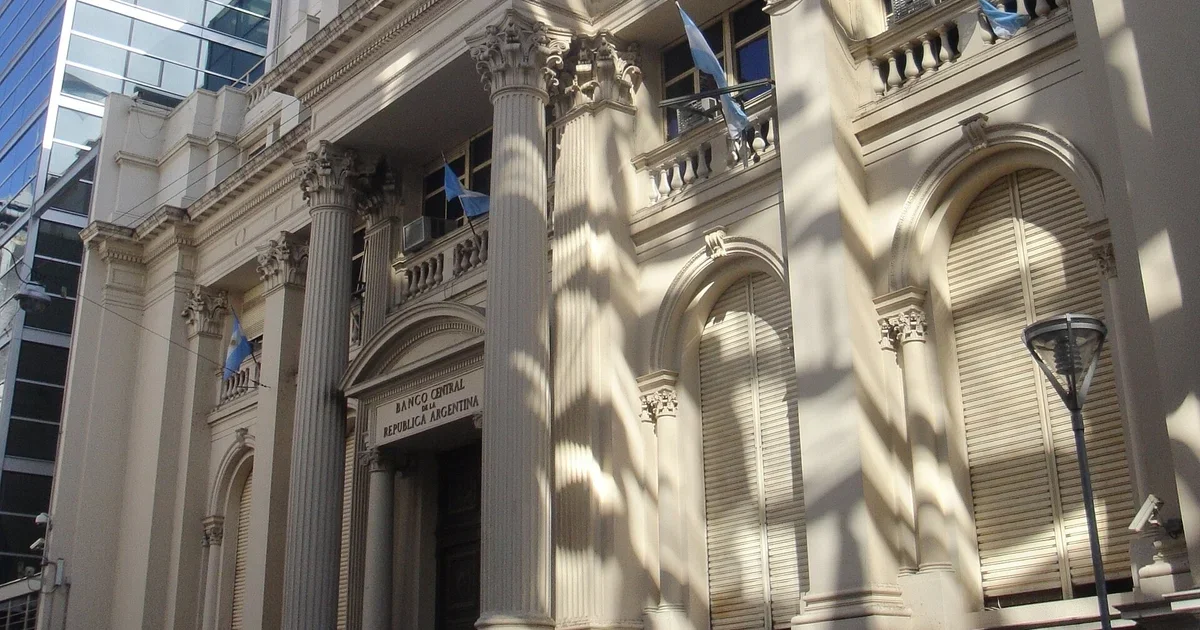
De acuerdo con el último Informe sobre Bancos del Banco Central de la República Argentina (BCRA), el ratio de irregularidad de los préstamos destinados a las familias se ubicó en el 12,2% durante septiembre. La cifra representó una disminución de 0,61 puntos porcentuales frente a agosto.
Sin embargo, la comparación interanual muestra un escenario diferente. El indicador se encuentra 4,9 puntos porcentuales por encima del nivel registrado en septiembre de 2025, lo que refleja el deterioro que atravesó la capacidad de pago de los hogares durante los últimos doce meses.
Original excerpt in Spanish. The content belongs to Perfil.